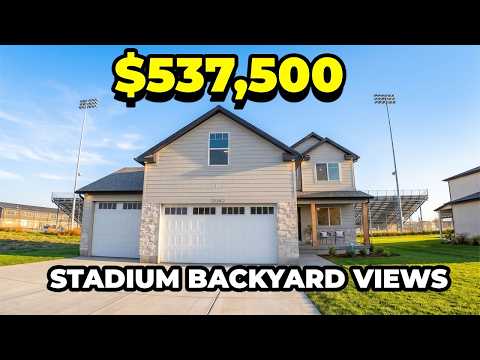
This Taylor Utah house for sale packs five bedrooms, a fully finished walkout basement, and up to $31,000 in builder credit into a $784,775 Nilson Homes new build on 0.36 acres.
Key Takeaways
- $784,775 new construction by Nilson Homes at 1838 S Chalgrove Rd in Taylor, Utah.
- Up to $31,000 builder credit can go toward a rate buydown or closing costs.
- Fully finished walkout basement adds 3 bedrooms, a full bath, and a massive bonus room.
- A private side-yard entrance and rough-in plumbing create ADU and house-hack potential.
- Hill AFB's South Gate is about 19 minutes away; Snowbasin is about 37 minutes away.
See What's For Sale Right Now
Browse every active Northern Utah listing on a live map — updated straight from the MLS.
In this article
- What Makes This Taylor Utah House for Sale Stand Out?
- How Does the Main-Level Living Layout Work?
- What Are the Kitchen and Great Room Like?
- What Do You Get in the Finished Walkout Basement?
- Could This Home Work as an ADU or House Hack?
- How Big Are the Lot, Deck, and Garage?
- How Can You Use the $31,000 Builder Credit?
- Can VA Loan Buyers Use Builder Incentives?
- Is This New Build Practical for a PCS to Hill AFB?
- What Schools and Recreation Are Near This Home?
- How Much Cash Do You Need to Buy This $784,775 Home?
- Is a New Build in Taylor Better Than a Resale Home Nearby?
- Who Is This 5-Bedroom Taylor Home Best For?
- What Does the Move-In Timeline Look Like for This New Build?
- What Will It Cost to Own This Home Each Month?
- What Should You Do Before Buying This New Build?
What Makes This Taylor Utah House for Sale Stand Out?
This Taylor Utah house for sale is a $784,775 Nilson Homes new build with 5 bedrooms, main-level living, a finished walkout basement, a 0.36-acre lot, and up to $31,000 in builder credit.
The home sits at 1838 S Chalgrove Rd in Taylor, Utah, in the western part of Weber County. Many new builds give you a nice main floor and leave the basement unfinished. This one comes with both levels finished.
That matters because finishing a basement later is a separate project with its own budget and timeline. Here, the bedrooms, bath, and bonus room are already part of the home.
Here is the quick snapshot:
- Price: $784,775
- Builder: Nilson Homes
- Bedrooms: 5
- Lot: 0.36 acres
- Garage: 3-car extended
- Incentive: up to $31,000 builder credit
New-build pricing and incentives can change, so confirm current details before you make plans. You can also compare this home against other options when you browse live MLS listings across Northern Utah.
How Does the Main-Level Living Layout Work?
You can handle daily life on one floor. The main level holds the open kitchen, great room, primary spa suite, guest bedroom and bath, mudroom, and laundry.
Main-level living is one of the biggest draws of this floor plan. Your bedroom, your laundry, and your kitchen all sit on the same floor, so you don't need the stairs for everyday routines.
The primary spa suite gives you a private retreat on this level. A separate guest bedroom and bath also sit on the main floor, which works well for visitors or a home office.
The mudroom gives you a place to drop boots, bags, and gear before they reach the rest of the house. With the laundry on the same level, you skip the trip downstairs with every load.
If you plan to stay in a home for many years, this layout can age well. The basement stays useful, but you never have to rely on it for day-to-day living.
What Are the Kitchen and Great Room Like?
The kitchen is open to the living space and includes double ovens and a walk-in pantry. The adjoining great room features a custom fireplace as its focal point.
If you cook often, double ovens are more than a nice extra. You can roast in one and bake in the other, which makes holidays and big gatherings easier to manage.
The walk-in pantry helps keep small appliances, bulk items, and snacks out of sight. That keeps your counters clear, which matters more in an open kitchen where everything is on display.
The great room's custom fireplace anchors the main living space. Because the kitchen stays open, whoever is cooking can still be part of the conversation.
When you tour, take a close look at how you'd place your furniture and where you'd want your table. The video gives you a great feel for the flow, but standing in the room will tell you even more.
What Do You Get in the Finished Walkout Basement?
The fully finished walkout basement includes 3 guest bedrooms, a full bath, a massive bonus room, a utility room, cold storage, rough-in plumbing, and a private side-yard entrance.
The basement is where this home really separates itself. With three bedrooms down here, the home's total reaches five without crowding the main floor.
The massive bonus room gives you flexible space. You could set it up as a media room, a home gym, a game room, or a place for long-term guests to spread out.
Practical features round out the level:
- Cold storage for food and seasonal items
- A utility room that keeps equipment separate from living areas
- Rough-in plumbing for possible future use
- A private side-yard entrance for independent access
Ask the builder exactly what the rough-in plumbing is intended to support. That answer will help you estimate any future project and its cost.
Could This Home Work as an ADU or House Hack?
Possibly. The private side-yard entrance, rough-in plumbing, and separate bedrooms create ADU and house-hack potential, but you should confirm current zoning, permit, and lending rules before counting on rental income.
A house hack means you live in the home and rent out part of it to help offset your housing costs. This basement has several of the physical pieces that make that idea possible.
Potential is not the same as permission, though. Before you run the numbers, check these items:
- Ask Weber County what its rules require for an accessory dwelling unit at this address.
- Check whether any community rules or covenants limit rentals.
- Price out what it would cost to add a kitchen or other features using the rough-in.
- Ask your lender whether any future rental income can count toward qualifying.
Even if you never rent it out, the same setup can suit multi-generational living or long-stay guests who want some privacy. That flexibility can be valuable whether or not you ever collect rent.
How Big Are the Lot, Deck, and Garage?
The home sits on a 0.36-acre lot with a covered back deck and a 3-car extended garage, giving you outdoor room, shaded space, and extra storage for vehicles and gear.
A 0.36-acre lot gives you room to plan your outdoor space. Think about where you'd want a garden, a play area, or a spot for entertaining.
The covered back deck extends your living space outside. Cover from the sun and weather means you can use it more often across Utah's changing seasons.
The 3-car extended garage is a real plus if you own trucks, ski gear, bikes, or tools. Extra depth can help with larger vehicles and storage, but bring your measurements if you have something specific to fit.
Because this is a new build, ask what landscaping and fencing are included. Those costs can add up, and this is a good item to clarify before you write an offer.
How Can You Use the $31,000 Builder Credit?
The builder offers up to $31,000 you can apply toward a rate buydown or closing costs. That is roughly 4% of the $784,775 price, and the best use depends on your goals.
A rate buydown can lower your monthly payment. Putting the credit toward closing costs reduces the cash you need at the closing table. Your lender can run both scenarios side by side.
| Use of credit | Main benefit | Often fits you if |
|---|---|---|
| Rate buydown | Lower interest rate and monthly payment | You plan to keep the home and loan for a while |
| Closing costs | Less cash needed at closing | You want to protect your savings for moving or setup costs |
Ask for a written breakdown of the credit, including any conditions attached to it. "Up to" means the amount and terms should be confirmed for your specific contract.
Also ask how many months it would take for a buydown to pay for itself. That break-even point is the simplest way to compare your options.
Can VA Loan Buyers Use Builder Incentives?
Yes. VA loan buyers can pair their benefits with builder incentives on this home, but your lender should confirm how the credit is structured so it fits VA rules.
According to the U.S. Department of Veterans Affairs, VA-backed purchase loans can offer benefits such as no required down payment in many cases and no private mortgage insurance. A VA funding fee may apply unless you qualify for an exemption.
That can make a strong pairing with a builder credit. Your VA benefit may reduce your cash needed up front, while the credit can help with closing costs or a lower rate.
Keep these points in mind:
- Entitlement matters. At this price, ask your lender to review your entitlement and your maximum loan amount.
- Concession limits exist. VA has rules on seller concessions, so the credit's structure matters.
- Occupancy is required. VA loans are for homes you will live in as your primary residence.
Work with a lender who closes VA loans on new construction regularly. That experience helps you avoid surprises with appraisal and credit questions.
Is This New Build Practical for a PCS to Hill AFB?
Yes, for many buyers. The home is about 19 minutes from Hill AFB's South Gate and offers VA-friendly incentives, flexible bedrooms, and a finished basement you won't need to complete after moving.
A PCS move leaves you little time for big projects. A finished new build means you can focus on settling in rather than coordinating basement contractors right after you arrive.
Drive time is only one part of your commute, so test it at the hours you'd actually travel if you can. Check the official Hill Air Force Base website for current base information, and confirm which gate you will use most.
If you are buying from out of state, start with our PCS relocation guide for Hill AFB. It can help you plan your timeline and compare areas before your orders take effect.
Also think ahead to your next move. A walkout basement with a separate entrance and five bedrooms may give you more options if you someday sell. Talk through resale and rental plans before you commit, since VA occupancy rules apply when you buy.
Free PCS to Utah Relocation Guide
Get my Hill AFB relocation packet — neighborhoods, VA loan tips, schools, and timelines — sent to your inbox.
What Schools and Recreation Are Near This Home?
The home falls in the Weber County School District, with Haven Bay Elementary, Mountain View Junior High, and West Field High. Snowbasin is about 37 minutes away for skiing and mountain recreation.
Assigned schools listed for this address are:
- Elementary: Haven Bay Elementary
- Junior high: Mountain View Junior High
- High school: West Field High
School boundaries can change, so verify the current assignment through the Weber School District website if this is a key factor for you.
Outdoor access is a big part of living in this area. A roughly 37-minute drive to Snowbasin makes a winter ski day or a summer mountain trip easy to fit into your weekend.
Taylor sits in the western part of the county, near communities like West Haven. For a wider view of the area, explore our Weber County community guide.
How Much Cash Do You Need to Buy This $784,775 Home?
Plan on $0 to about $157,000 down, depending on the loan. Closing costs usually run 2-3% of the price. The up to $31,000 builder credit can cover most or all of those costs.
At $784,775, your cash to close depends mostly on your loan type. VA buyers with full entitlement can put $0 down. Conventional buyers often choose 5%, 10%, or 20% down. Here is a quick look at the math.
| Down payment | Cash down | Loan amount |
|---|---|---|
| 0% (VA) | $0 | $784,775 + funding fee |
| 5% | $39,239 | $745,536 |
| 10% | $78,478 | $706,297 |
| 20% | $156,955 | $627,820 |
On top of the down payment, closing costs in Utah usually land around 2-3% of the price. That is roughly $15,700 to $23,500 here. It covers lender fees, title insurance, prepaid taxes, and homeowners insurance. This is where the up to $31,000 builder credit really shines. It can wipe out most or all of those costs and still leave room to lower your rate.
Also budget a few thousand dollars for things the builder does not include. Think window coverings, backyard landscaping, and a fridge if one is not part of the package. Ask for a written list of included items before you sign.
Is a New Build in Taylor Better Than a Resale Home Nearby?
For many buyers, yes. You get modern systems, a builder warranty, and up to $31,000 in incentives. A resale may offer mature trees and a lower price, but often needs updates soon.
Western Weber County has both new construction and older resale homes. Each path has trade-offs. The right choice depends on your budget, timeline, and how much work you want to take on.
- Big incentives: Resale sellers rarely offer $31,000 toward your rate or closing costs. Builders often do.
- Lower upkeep: A new roof, furnace, water heater, and appliances mean fewer surprise repair bills in the first years.
- Energy efficiency: Newer insulation, windows, and HVAC usually mean lower utility bills than a 20-year-old home.
- Warranty coverage: Builders typically back their work for a set period. Resale homes are sold as-is unless you buy a home warranty.
- Modern layout: Main-level living, a walk-in pantry, and a finished walkout basement are harder to find in older homes.
A resale may win if you want mature landscaping, an established street, or a lower price point. Just factor in the cost of updates like flooring, paint, or an aging furnace. Those can add up fast.
Want to compare side by side? You can browse current Northern Utah listings and see how resale prices in Taylor and nearby West Haven stack up against this Nilson Homes build.
Who Is This 5-Bedroom Taylor Home Best For?
It fits growing families, multigenerational households, and Hill AFB military families who want main-floor living plus a separate, flexible basement for guests, teens, or rental income.
This home has a rare mix: single-level living upstairs and a fully finished walkout basement below. That setup works for a lot of different households.
- Growing families: Five bedrooms means room for kids now and later. The massive bonus room can be a playroom, gym, or movie space.
- Multigenerational living: Grandparents or adult kids can have their own space downstairs with a private side-yard entrance.
- Military families: A 19-minute drive to the Hill AFB South Gate and a layout that could rent well later make it a smart long-term hold if orders take you elsewhere.
- Buyers planning to age in place: The primary spa suite, laundry, and kitchen are all on the main level. Fewer stairs every day.
- Outdoor lovers: Snowbasin is about 37 minutes away, and the 3-car extended garage has room for skis, bikes, and toys.
It may not be the best fit if you want a tiny yard with zero upkeep. A 0.36-acre lot is a real yard. You will want a plan for mowing, sprinklers, and snow removal. For most buyers in this price range, though, that extra space is exactly the point.
What Does the Move-In Timeline Look Like for This New Build?
If the home is complete, you can often close in 30 to 45 days. Get pre-approved first, lock your incentive early, and schedule inspections and the final walkthrough before closing.
Buying new construction follows a slightly different path than a resale. Here is a simple timeline if the home is finished or close to it.
- Week 1 - Pre-approval: Talk to a lender and get a full pre-approval. If you are using a VA loan, request your Certificate of Eligibility now.
- Week 1-2 - Contract: Write an offer on the Nilson Homes contract. Confirm in writing how the up to $31,000 credit will be used.
- Week 2-3 - Inspection and appraisal: Order your independent inspection. Your lender orders the appraisal.
- Week 3-5 - Underwriting: Send documents fast. Lock your rate, and finalize any buydown with the builder's credit.
- Final week - Walkthrough and closing: Walk the home with the builder, note any punch-list items, then sign and get your keys.
Moving on PCS orders? Many military buyers start the search before they arrive. Video tours, remote inspections, and e-signing make that easier. Our PCS relocation guide for Hill AFB walks through each step. You can also check base updates on the official Hill AFB website.
What Will It Cost to Own This Home Each Month?
Expect principal and interest plus property taxes, homeowners insurance, and utilities. Weber County property taxes are relatively low, and new-build efficiency helps keep utility bills in check.
Your mortgage payment is only part of the picture. To budget well, add up all the monthly costs of owning a $784,775 home in western Weber County.
- Principal and interest: This depends on your rate and down payment. Using the builder credit for a rate buydown can lower this number for years.
- Property taxes: Utah's effective property tax rates are among the lower ones in the country. Owner-occupied homes also get a primary residence exemption on part of the value.
- Homeowners insurance: New construction often costs less to insure thanks to a new roof and modern wiring.
- Utilities: Gas, power, water, sewer, and trash. A home this size uses more, but newer systems help.
- HOA dues: Ask whether the subdivision has an HOA and what it covers.
If you rent out the walkout basement later, that income can offset a big piece of the payment. Just check local rules first.
Want to know how western Weber stacks up on taxes, utilities, and home prices? Our Weber County community guide breaks it down. Or call Donald at (801) 603-5213 for a real payment estimate on this home.
What Should You Do Before Buying This New Build?
Get pre-approved, tour the home with your own agent, ask for the builder's incentive and warranty terms in writing, and arrange an independent inspection before closing.
Buying new construction is different from buying a resale home. The builder's sales team represents the builder, so it helps to have your own agent looking out for you.
Follow these steps:
- Get pre-approved and compare the builder credit scenarios with your lender.
- Tour the home and check the basement entrance, storage, and deck in person.
- Get the terms in writing, including the credit, warranty coverage, and included items.
- Order an independent inspection, even though the home is brand new.
- Confirm your closing timeline, especially if you are tied to PCS dates.
Ready to see it? Call Donald I. Gomez and The DIG Team at (801) 603-5213 to set up a private showing or a live video walkthrough.
Thinking About a Move? Let's Talk.
Call Donald I. Gomez for straight answers on Northern Utah real estate — no pressure, just local help.
Frequently Asked Questions
How much is the new build at 1838 S Chalgrove Rd in Taylor, Utah?
How many bedrooms does this Taylor home have?
Is the basement finished, or would I need to finish it myself?
Can I rent out the basement of this home?
How far is this home from Hill Air Force Base?
Can I use a VA loan with the $31,000 builder credit?
Which schools serve this home in Taylor?
How can I tour this home or see similar listings?
Does the VA funding fee apply if I buy this Taylor home with $0 down?
Can I use the $31,000 builder credit for both a rate buydown and closing costs?
Donald I. Gomez
Donald helps buyers, sellers, and PCSing military families move across Northern Utah — from Ogden to the Wasatch. A longtime Hill AFB-area local, he tours new builds and resale homes every week on his YouTube channel.