If you are a first time home buyer in Ogden Utah, you are shopping the most affordable real city on the northern Wasatch Front — and one of the few with its own down payment assistance program.
Key Takeaways
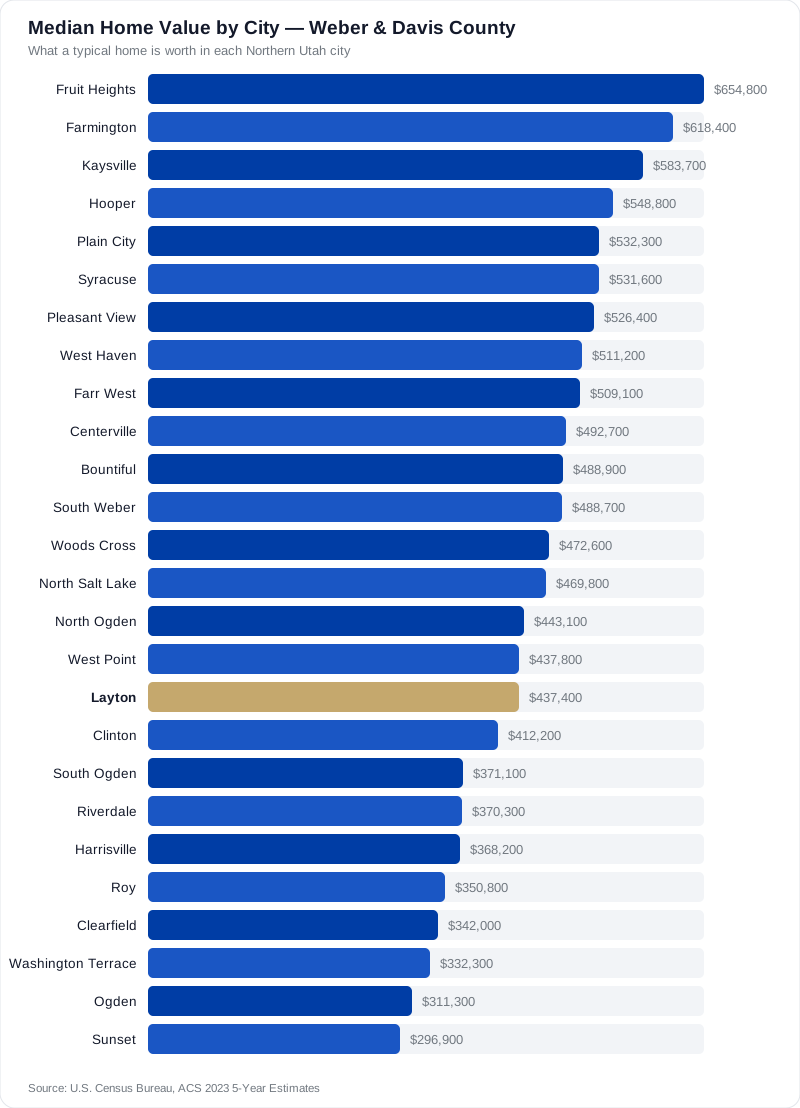
- Ogden's median home value is $311,300 — the lowest of any major Weber or Davis city.
- Own in Ogden offers $10,000 to $20,000 in 0% deferred down payment help.
- Utah Housing down payment assistance only works with a Utah Housing first mortgage.
- Get pre-approved by an approved participating lender before you tour homes.
- Ogden's older housing stock means inspections matter more here than in new-build suburbs.
See What's For Sale Right Now
Browse every active Northern Utah listing on a live map — updated straight from the MLS.
In this article
- What should a first time home buyer in Ogden Utah know before starting?
- Does Utah offer first time home buyer programs?
- How does the Own in Ogden down payment assistance program work?
- Who qualifies for Own in Ogden?
- What is the Utah first time home buyer program through Utah Housing?
- What are the general first time home buyer Utah requirements?
- How much cash do you actually need to close in Ogden?
- What is different about buying an older home in Ogden?
- Should you buy in Ogden or a nearby city?
- Does buying in Ogden beat renting?
- Who should NOT buy their first home in Ogden?
- What should you do first as a first time home buyer in Ogden?
What should a first time home buyer in Ogden Utah know before starting?
Ogden is the most affordable entry point on the northern Wasatch Front, with a median home value of $311,300. Get pre-approved first, then check whether you qualify for Ogden City's own down payment assistance program before writing an offer.
Here is the short version of what makes Ogden different. According to the U.S. Census Bureau's American Community Survey 2023 5-year estimates, Ogden's median home value is $311,300 and the median household income is $70,053. Population is 86,973.
Compare that to Layton at $437,400 or Kaysville at $583,700 and the picture is clear. Ogden is where a normal Northern Utah income still buys a house.
The second thing to know: Ogden City runs its own assistance program, separate from anything the state offers. Most buyers I meet have never heard of it, and it can be worth up to $20,000.
The third thing: Ogden's homes are older than the suburbs south of it. That is a feature and a risk, and it changes how you inspect and how you budget. We cover all three below. You can also browse live MLS listings as you read to see what your number actually buys.
Does Utah offer first time home buyer programs?
Yes. Utah Housing Corporation offers down payment assistance as a second loan paired with its own first mortgage, and Ogden City separately runs Own in Ogden, a 0% interest deferred loan of $10,000 to $20,000.
There are two layers of help available to a Utah first time home buyer shopping in Ogden, and they come from completely different places.
- Statewide: Utah Housing Corporation (UHC) — down payment assistance structured as a second loan.
- City level: Own in Ogden — Ogden City's deferred-payment down payment assistance loan.
People search for utah first time home buyer grants, but read the fine print on both of these. Neither one is a check with no strings attached.
Both are structured as loans. The difference is that they may cost you nothing monthly, and one version can effectively go away after ten years. That distinction matters, because it changes what happens when you sell or refinance. I break each one down next.
How does the Own in Ogden down payment assistance program work?
Own in Ogden is a 0% interest, deferred-payment loan: $10,000 for general buyers, $15,000 for K-12 teachers, administrators, and Ogden City employees, and $20,000 for Ogden City police officers and firefighters.
This is the single most valuable thing on this page, so read it carefully. According to Ogden City, Own in Ogden provides a 0% interest, deferred-payment loan in three tiers:
- $10,000 for general buyers
- $15,000 for K-12 teachers and administrators, and Ogden City employees
- $20,000 for Ogden City police officers and firefighters
Deferred means no monthly payment. Ogden City states that repayment comes due when you sell the home, refinance the mortgage, or the home stops being your primary residence.
Here is the part that makes it exceptional for first responders. For sworn Ogden City police officers and firefighters, the repayment requirement expires after 10 years of continued owner-occupancy and continued Ogden City employment. Stay ten years, keep the job, live in the house — the obligation goes away.
The program is open for home closings occurring on or after July 1, 2026. Confirm current availability and funding directly with Ogden City before you plan around it.
Who qualifies for Own in Ogden?
Households cannot exceed 80% of area median income — for a single-person household the maximum gross income is $66,050. You must contribute at least $500 and occupy the home as your primary residence. Non-occupant borrowers are not eligible.
Per Ogden City, the confirmed eligibility rules are:
- Household income at or below 80% of area median income. For a single-person household, the maximum gross income is $66,050. Larger households have higher limits — ask the City for the current chart matching your household size.
- You must contribute at least $500 of your own money.
- You must occupy the home as your primary residence.
- Non-occupant borrowers are not eligible. This is the rule that trips people up.
That last one kills a common workaround. If your plan was to have a parent co-sign who will not live in the house, that structure does not work with Own in Ogden. The people on the loan need to be the people living there.
Note the income ceiling against local reality. Ogden's median household income is $70,053 per the ACS 2023 5-year estimates. A typical single earner in Ogden may well fit under the limit. A dual-income household often will not. Check the actual chart before you assume either way.
What is the Utah first time home buyer program through Utah Housing?
Utah Housing Corporation offers down payment assistance as a second loan available only in combination with a Utah Housing first mortgage. It cannot be paired with an outside lender's loan, and you qualify through a UHC approved participating lender.
This is the detail that costs Utah buyers the most money, so I will say it plainly. Utah Housing Corporation states that its down payment assistance is a second loan available only in combination with a Utah Housing first mortgage. It cannot be paired with an outside lender's loan.
So if you shop rates at your credit union, fall in love with their offer, and lock it, you have just made yourself ineligible for UHC assistance on that purchase. The first mortgage and the assistance are a package deal.
You qualify through a Utah Housing approved participating lender. Not every loan officer in Weber County is one. Ask that question in your very first phone call.
Two more confirmed points from UHC: credit scores above 620 are permitted, and a higher credit score may qualify you for a lower monthly payment. Utah Housing also now offers a Deferred Down Payment Assistance option. Program-specific percentages and per-program credit minimums float around on third-party mortgage blogs — I am not repeating them here, because they are not confirmed on Utah Housing's own site. Get those numbers from UHC or your approved lender.
What are the general first time home buyer Utah requirements?
Expect a lender to verify income, employment, credit, and assets. Expect assistance programs to add income caps, an owner-occupancy requirement, a minimum personal contribution, and sometimes homebuyer education. Requirements vary by program, so confirm with the program itself.
There is no single statewide checklist, which is why this question is so frustrating to search. What exists is a stack of requirements coming from three directions.
- Your loan type. Conventional, FHA, VA, and USDA each set their own credit, down payment, and property standards. Your lender applies them.
- Your lender's overlays. Individual lenders can require more than the loan program's published minimum.
- Your assistance program. Own in Ogden adds the 80% AMI cap, the $500 contribution, and owner-occupancy. Utah Housing adds the requirement that its own first mortgage be used.
What I tell every buyer: the order of operations determines whether you qualify, not just your numbers. Talk to a Utah Housing approved participating lender before you talk to anyone else, because that one conversation opens or closes the most doors.
If you are military or a veteran, VA financing is its own path with its own entitlement rules. That is a separate topic covered in depth elsewhere on the site — start at the VA home loan page for the official version, then bring it to your lender.
How much cash do you actually need to close in Ogden?
More than the down payment. Budget for earnest money, a home inspection, an appraisal, closing costs, and prepaid taxes and insurance. Your lender's Loan Estimate lists every line item in dollars within three business days of applying.
The down payment gets all the attention. It is rarely the whole number.
Costs a first-time Ogden buyer should plan for:
- Earnest money — deposited when your offer is accepted, credited back to you at closing
- Home inspection — paid out of pocket, before you are fully committed
- Appraisal — ordered by your lender
- Closing costs — lender fees, title, and recording
- Prepaids — property taxes and homeowners insurance collected in advance
I am not going to quote you dollar figures for these. They move with the price, the lender, and the title company, and a made-up number does you no favors. Your Loan Estimate is the real answer — federal rules require your lender to put it in writing within three business days of your application.
Where assistance helps: Own in Ogden's $10,000 to $20,000 reduces what you bring to the table. But remember, you still must put in at least $500 of your own money. That minimum is not waivable.
Free PCS to Utah Relocation Guide
Get my Hill AFB relocation packet — neighborhoods, VA loan tips, schools, and timelines — sent to your inbox.
What is different about buying an older home in Ogden?
Ogden's core neighborhoods are full of pre-war and mid-century homes. Expect to look hard at the electrical panel, sewer line, foundation, roof age, and any unpermitted basement work. The inspection is not optional here.
Ogden is an old railroad town, and the housing shows it. In the East Central and Jefferson areas you will find brick bungalows and Victorians with real craftsmanship. Out toward the newer western and northern edges, the stock gets younger.
Character comes with a maintenance history. On older Ogden homes I want eyes on:
- The electrical panel, and whether the home still has knob-and-tube or aluminum branch wiring
- The main sewer line — a scope is cheap compared to a dig
- Foundation and grading, especially up on the benches where drainage matters
- Roof age and any evidence of ice damming
- Unpermitted basement apartments, which are common here and can affect financing and insurance
None of this is a reason to avoid Ogden. It is a reason to hire a good inspector and write your offer with the right contingencies. An inspection that finds a bad sewer line before closing is the best money you will spend all year.
For well, septic, and environmental questions on properties at the edge of the city, the Weber-Morgan Health Department is the right reference — see weber-morgan.org.
Should you buy in Ogden or a nearby city?
Ogden gives you the lowest entry price and the only city-level down payment assistance in the area. Roy, Clearfield, and North Ogden cost more but offer newer housing stock. Compare the price gap against what you actually get.
Here is the honest side-by-side, using ACS 2023 5-year estimates from the U.S. Census Bureau.
| City | Median home value | Median household income | Median gross rent |
|---|---|---|---|
| Ogden | $311,300 | $70,053 | $1,128 |
| Roy | $350,800 | $91,112 | $1,557 |
| Clearfield | $342,000 | $75,429 | $1,459 |
| North Ogden | $443,100 | $107,425 | $1,405 |
| Layton | $437,400 | $99,188 | $1,455 |
Ogden sits roughly $39,500 below Roy and $131,800 below North Ogden at the median. That gap is the trade: you get in cheaper, and you take on an older house.
And remember, only Ogden has Own in Ogden. If you qualify for the $20,000 first-responder tier, the effective gap widens further. Browse the Weber County community pages or the Davis County community pages to compare neighborhoods block by block.
Does buying in Ogden beat renting?
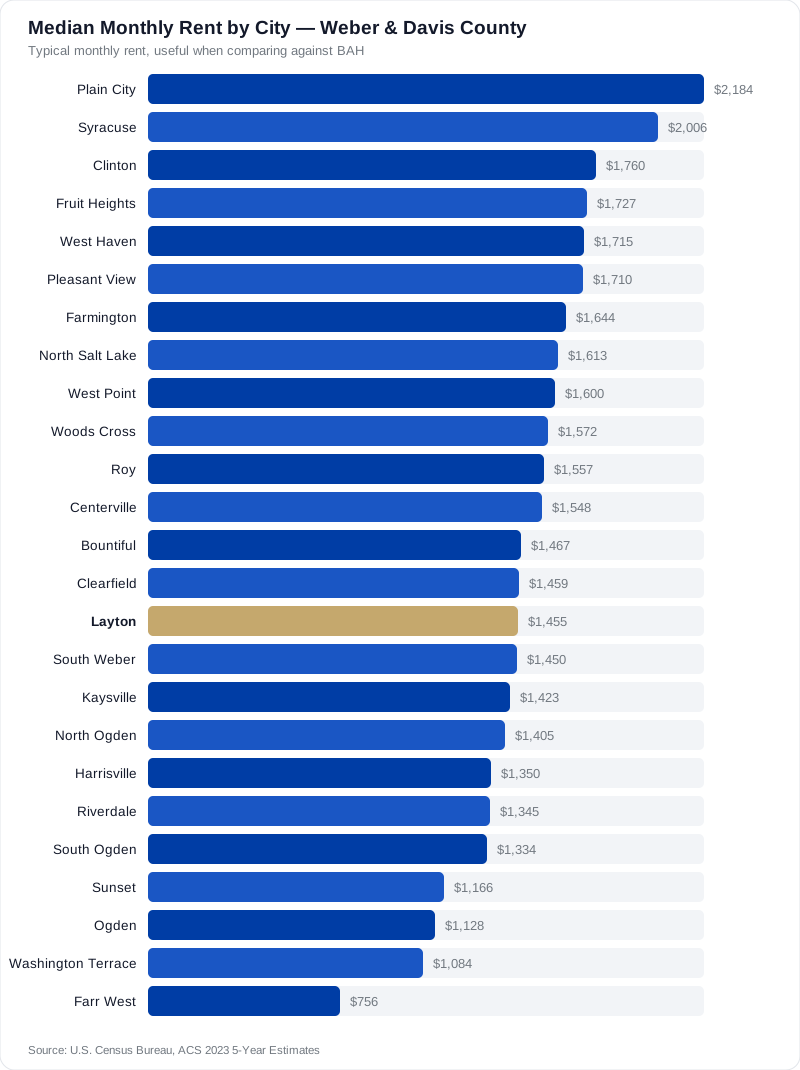
Ogden's median gross rent is $1,128, the lowest of the cities compared here, so renting is genuinely cheap in Ogden. Buying wins on equity and payment stability, not necessarily on month-one cost.
I will not pretend the math is automatic. Per ACS 2023 5-year estimates, Ogden's median gross rent is $1,128. Roy's is $1,557 and Farmington's is $1,644. Ogden renters pay less than almost anyone else on the northern Wasatch Front.
What buying gives you that renting does not:
- A fixed principal and interest payment that does not renew every twelve months
- Equity instead of receipts
- Access to $10,000 to $20,000 in Own in Ogden assistance that no renter can use
What renting gives you: flexibility, and no responsibility for that sewer line.
My rule of thumb — if you are staying in the area at least three to five years, buying usually wins. If you are unsure whether you will still be here next summer, renting in Ogden is not a bad place to wait it out.
Who should NOT buy their first home in Ogden?
Skip Ogden for now if you cannot cover an inspection and a repair reserve, if your income sits just above the 80% AMI cap without enough savings, or if you may relocate within two years.
I would rather lose the deal than watch someone get in over their head. Ogden is the wrong first purchase if:
You have no repair reserve. Older homes break. If every dollar goes into the down payment and there is nothing behind it, a water heater becomes a crisis. Wait three months and build the cushion.
You are just over the income cap with thin savings. This is the most awkward spot to be in — too much income for Own in Ogden's 80% AMI limit, not enough saved to close comfortably. Sometimes the answer is a Utah Housing loan without the city program. Sometimes the answer is six more months.
You might move within two years. Transaction costs on both ends eat short-term ownership. And remember, Own in Ogden repayment triggers when the home stops being your primary residence — which matters if you are eyeing a PCS or a job transfer and thinking about renting the place out.
You want brand-new construction with a three-car garage under $320,000. That is not Ogden. That is a different city and a different budget, and I will tell you that on the first call instead of the fifth showing.
Who Ogden is right for: a buyer with steady Northern Utah income, patience for an older house, and a plan to stay put. That describes most of the people I close with.
What should you do first as a first time home buyer in Ogden?
Call a Utah Housing approved participating lender, get a written pre-approval, confirm your Own in Ogden eligibility with Ogden City, set your true all-in budget, then tour homes with an agent who knows Ogden's neighborhoods.
The order matters more than the speed. Do it like this.
- Call a Utah Housing approved participating lender. Ask directly: are you a UHC approved participating lender? If the answer is no, keep dialing. This step preserves your options.
- Get a written pre-approval, not a verbal "you're probably fine." Sellers in Weber County do not take offers seriously without one.
- Confirm eligibility with Ogden City for the income limit matching your household size, plus current program funding.
- Set your all-in monthly number — principal, interest, taxes, insurance, and any HOA — not just the purchase price.
- Tour with an agent who knows the blocks. Ogden changes character street to street in a way no map can show you.
Moving in from out of state or connected to Hill Air Force Base? Two things will save you weeks: our PCS relocation guide for Hill AFB and the free 208-page relocation guide. Both are built for people who have never seen Northern Utah and have thirty days to decide.
When you are ready, search live MLS listings and call me at (801) 603-5213. I will tell you straight whether the house is worth the price and whether the timing is right for you.
Thinking About a Move? Let's Talk.
Call Donald I. Gomez for straight answers on Northern Utah real estate — no pressure, just local help.
Frequently Asked Questions
Does Utah offer first time home buyer programs?
Are there Utah first time home buyer grants that never have to be repaid?
How much is Own in Ogden down payment assistance?
What is the income limit for Own in Ogden?
Can I use Utah Housing down payment assistance with my own lender?
What credit score do I need as a first time home buyer in Utah?
Is Ogden a good place to buy a first home?
Can my parents co-sign on an Ogden first-time buyer purchase?
Donald I. Gomez
Donald helps buyers, sellers, and PCSing military families move across Northern Utah — from Ogden to the Wasatch. A longtime Hill AFB-area local, he tours new builds and resale homes every week on his YouTube channel.